Business Cover Solutions :: News
SHARE

Share this news item!

Why climate resilience is becoming an insurance issue for SMEs

Natural hazard planning is moving from a property concern to a business continuity priority

Why climate resilience is becoming an insurance issue for SMEs?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

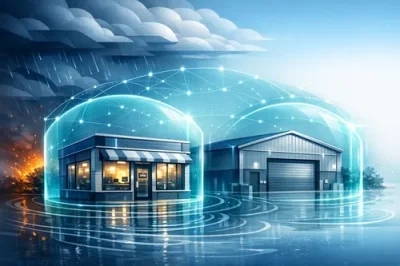
Fresh industry attention on climate resilience is a timely reminder for Australian small and medium-sized businesses that insurance affordability is increasingly linked to the physical risks around premises, supply chains and local infrastructure.
The latest discussion has focused on the need for stronger mitigation, better land-use decisions and more practical investment in disaster resilience, rather than relying on insurance alone after floods, storms, bushfires or cyclones occur.

For business owners, the message is not simply that premiums may rise in higher-risk locations. The more important point is that insurers are looking closely at how vulnerable a business is to disruption. A café in a flood-prone strip, a warehouse near bushland, a regional motel exposed to storm damage, or a trades business dependent on a single road access point can all face different underwriting questions, even if their claims history is clean.

This matters because climate-related risk can affect several sections of a business insurance program at once. Commercial property insurance may respond to insured damage to buildings, contents, stock and equipment. Business interruption insurance may help replace lost income after an insured event, but only within the limits, waiting periods and definitions in the policy. Public liability exposures can also shift if damaged premises, temporary worksites or customer access create safety issues after severe weather.

The practical step for SMEs is to treat resilience as part of the annual insurance review, not as a separate facilities task. Owners should reassess whether asset values reflect current reinstatement costs, whether stock peaks are captured, whether backup suppliers and alternative premises are realistic, and whether interruption cover allows enough time for rebuilding, approvals and customer recovery. Businesses can also estimate appropriate sums insured before renewal to reduce the risk of carrying outdated limits.

Risk controls are becoming more important too. Drainage maintenance, firebreaks, secure storage of portable equipment, storm-rated roofing, surge protection, data backups and clear emergency procedures can all support a stronger risk profile. These measures may not guarantee cheaper cover, but they can help present the business as better managed when insurers assess terms.

Where the exposure is complex, working with a broker can help SMEs compare wording, exclusions and sub-limits rather than focusing only on headline premium. As climate risk continues to shape the Australian insurance market, the businesses best placed to adapt will be those that combine suitable cover with practical preparation before the next major event occurs.

Published:Wednesday, 9th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Why SME Insurance Confidence Still Needs a Reality Check
16 Sep 2026: Paige Estritori
The latest SME insurance research from Vero is a useful reminder that confidence and preparedness are not always the same thing. Many Australian small and medium-sized businesses know insurance is essential, but the harder question is whether their current cover would respond as expected after a major loss, liability claim or interruption. - read more
Why climate resilience is becoming an insurance issue for SMEs
09 Sep 2026: Paige Estritori
Fresh industry attention on climate resilience is a timely reminder for Australian small and medium-sized businesses that insurance affordability is increasingly linked to the physical risks around premises, supply chains and local infrastructure. The latest discussion has focused on the need for stronger mitigation, better land-use decisions and more practical investment in disaster resilience, rather than relying on insurance alone after floods, storms, bushfires or cyclones occur. - read more
What NSW insurance levy reform could mean for small businesses
02 Sep 2026: Paige Estritori
Renewed industry focus on reforming the New South Wales emergency services levy is a welcome development for many small and medium-sized businesses that have watched insurance costs absorb a growing share of operating budgets. The levy, which is charged through many insurance premiums, has long been criticised because it can make cover more expensive precisely for the businesses that choose to insure properly. - read more
Why SMEs Should Recheck Insurance Values Before Renewal
26 Aug 2026: Paige Estritori
Fresh industry attention on underinsurance is a timely reminder for Australian small and medium-sized businesses to look beyond last year’s policy schedule when renewing cover. As building materials, labour, equipment and specialist trades remain costly in many sectors, insured values that once looked reasonable may no longer reflect the true cost of getting a business back on its feet. - read more


Business Insurance Articles

Business Insurance Requirements in Australia: Legal, Contractual and Industry Rules
Business insurance requirements in Australia can come from legislation, contracts, licensing conditions and industry expectations. This guide explains the difference so business owners can identify which covers may be compulsory, required by clients or prudent for their risks. - read more
Key Risk Management Practices Every SME Should Implement
Risk management is an essential process for identifying, assessing, and prioritizing potential challenges that could impact the success of a business. For small and medium-sized enterprises (SMEs), effective risk management can mean the difference between thriving and merely surviving in a competitive landscape. - read more
Cyber Liability Insurance for Australian Small Businesses: Cover, Limits and Exclusions
Cyber liability insurance can help Australian small businesses manage the financial impact of cyber incidents, but cover varies widely. This guide explains common inclusions, exclusions, limits and questions to ask before choosing a policy. - read more
Understanding Business Insurance: What Every SME Owner Should Know
The world of trade businesses in Australia is constantly evolving, presenting both exciting opportunities and new challenges. As these businesses grow, so do the risks they face, making it crucial to consider protective measures. - read more

Knowledgebase
Insurance Policy Excess:
The amount you will have to contribute when you make a claim.